
Written by Duane Buziak, NMLS #1110647 | Coast2Coast Mortgage LLC NMLS #376205
If your mortgage payment feels like it’s crushing your budget every month, you’re not alone — and you’re not out of options. Short Pump and Henrico County homeowners are navigating a market where median home prices sit between $520,000 and $527,000, meaning even a modest rate improvement or program switch can return hundreds of dollars to your pocket each month.
This guide breaks down the most effective solutions available right now. Whether you bought at a higher rate, your income has shifted, or you’re still paying PMI you no longer need, at least one of these applies to your situation. Each option includes what it does, who it’s best for, and realistic numbers so you can make an informed decision — not just a hopeful one.
Before diving in: according to the FHFA 2026 conforming loan limit data, the baseline limit for Henrico County is $806,500 — meaning most Short Pump homeowners are well within conventional loan territory and have more refinance options than they may realize.
1. Short Pump Mortgage — Wholesale Rate Refinance & Broker Shopping
Best for: Short Pump and Henrico County homeowners who want the lowest available rate by shopping 500+ wholesale lenders simultaneously.
Short Pump Mortgage is an independent mortgage brokerage run by Duane Buziak, NMLS #1110647, that submits your loan to 500+ wholesale lenders simultaneously — accessing rate tiers that retail banks and direct lenders simply cannot offer their customers.
Where This Tool Shines
The core structural advantage here is access. A retail loan officer can only offer you their single institution’s rate sheet. An independent wholesale broker submits your file to hundreds of lenders at once, letting the market compete for your loan. That competition translates directly into lower rates and better terms for you.
The NoTouch Credit Pull is another standout feature. You can explore your refinance options, get actual rate quotes, and compare scenarios across multiple wholesale lenders without a single hard inquiry hitting your credit report. This matters especially if you’re still deciding whether to refinance — you don’t have to commit your credit score to find out what’s possible. This is what’s known as a soft credit pull mortgage or no hard inquiry mortgage pre approval.
Key Features
NoTouch Credit Pull: Soft pull pre-approval with no hard inquiry and no credit score impact — you can shop rates risk-free before committing.
500+ Wholesale Lenders: Simultaneous submission to the wholesale market, accessing pricing unavailable at retail banks or direct lenders.
Full Program Menu: FHA Streamline, VA IRRRL, USDA, Conventional, Non-QM, DSCR, and Bank Statement refinance options all available under one roof.
VA Loans to 500 FICO: One of the few brokers in Virginia offering VA financing down to a 500 credit score — named Virginia Broker of the Year 2024 and 2025.
Dynamo DPA and Turbo DPA: Down payment assistance programs available for purchase restructures, relevant when reconfiguring a loan scenario.
Real Dollar Math: What a Rate Refinance Looks Like
Here’s an illustrative scenario based on realistic Short Pump numbers. Assume a $480,000 loan balance (reasonable given the $520,000–$527,000 median with some equity built). At a 7.25% rate, your 30-year principal and interest payment runs approximately $3,274 per month. Drop that rate to 6.375% and the same loan costs approximately $2,996 per month — a savings of roughly $278 per month, or $3,336 per year.
On $6,000 in closing costs, that’s a break-even of approximately 21 to 22 months. These figures are illustrative estimates based on standard amortization and are not a guarantee of any specific rate or outcome — your actual numbers depend on credit, property, and current market conditions.
Best For
Homeowners in Short Pump, Glen Allen, and Henrico County who want to compare multiple lenders without commitment, borrowers with FHA, VA, USDA, or conventional loans, and anyone who has been quoted a rate by a retail lender and wants to know if the wholesale market can beat it.
Pricing
No broker fee on most wholesale transactions. Rate and fee disclosure provided upfront after soft pull review. Call (804) 212-8663 to start with a no-credit-hit mortgage application.
2. Sparrow Home Loans — Local Short Pump Retail Refinance
Best for: Short Pump and Henrico County borrowers who prefer face-to-face service with a local retail lender they already know.
Sparrow Home Loans, led by Briana Sparrow, operates in the Short Pump and Henrico County market through the Atlantic Bay Mortgage retail channel, offering conventional and FHA refinance products with a local presence.
Where This Tool Shines
Sparrow Home Loans offers something genuinely valuable: a local Short Pump face you can sit down with. For borrowers who prioritize relationship-based service and prefer working with someone embedded in the community, that matters.
The trade-off is structural. As a retail channel operation through Atlantic Bay, Sparrow Home Loans can only offer that single institution’s rate sheet. There’s no ability to shop the wholesale market or submit to competing lenders simultaneously — you’re getting one set of pricing from one source.
Key Features
Local Short Pump Presence: Face-to-face service option for Henrico County borrowers who prefer in-person consultation.
Conventional and FHA Refinance: Standard refinance products available through the Atlantic Bay retail channel.
Community Familiarity: Local market knowledge of Short Pump, West Broad Village, and surrounding neighborhoods.
Single-Shelf Pricing: Retail channel only — rate options are limited to one institution’s offerings.
Best For
Borrowers who have an existing relationship with Sparrow Home Loans or who strongly prefer in-person service over rate optimization. If the lowest available rate is your primary goal, comparing wholesale pricing alongside retail quotes is worth the extra step.
Pricing
Retail channel pricing; rates and fees vary. Contact Sparrow Home Loans directly for current rate quotes.
3. C&F Mortgage Corp — Virginia Regional Retail Refinance
Best for: Henrico County homeowners who want a Virginia-chartered regional institution with in-house underwriting.
C&F Mortgage Corp (NMLS #1551139) is a Virginia-based retail mortgage lender with in-house underwriting, offering rate-and-term refinance options for homeowners across Henrico County and the greater Richmond area.
Where This Tool Shines
C&F Mortgage Corp’s in-house underwriting is a legitimate operational advantage — decisions happen locally rather than being routed through a national underwriting center. For borrowers with straightforward conventional or FHA loans, that can mean faster turnaround and more direct communication during the process.
The structural limitation is the same as any retail lender: C&F Mortgage Corp operates from its own rate sheet. You’re working with one institution’s pricing, not a competitive wholesale market. For borrowers whose primary concern is payment reduction, that distinction is worth understanding before you commit.
Key Features
Virginia-Chartered Regional Institution: Local underwriting and processing team based in Virginia.
In-House Underwriting: Decisions made locally, which can improve communication and timeline predictability.
Conventional, FHA, and VA Refinance: Standard refinance product menu for existing homeowners.
Single Institution Pricing: Retail channel only — cannot access wholesale lender competition.
Best For
Henrico County borrowers who have an existing banking or mortgage relationship with C&F and prefer working within a Virginia-chartered institution. Comparing their retail quote against wholesale pricing is a straightforward way to determine whether you’re leaving money on the table.
Pricing
Retail channel pricing; contact C&F Mortgage Corp directly for current rate and fee disclosure.
4. Movement Mortgage — Retail Refinance with Speed-to-Close Focus
Best for: Borrowers who prioritize fast closing timelines and prefer working with a mission-driven retail lender.
Movement Mortgage is a retail lender with a stated emphasis on fast processing timelines and a community reinvestment model, offering conventional, FHA, and VA refinance products for existing homeowners.
Where This Tool Shines
Movement Mortgage has built a brand around speed-to-close and community focus. For borrowers who have had slow or frustrating refinance experiences elsewhere, the operational emphasis on faster timelines is a genuine differentiator within the retail lending space.
Like all retail lenders, Movement operates from a single institution’s rate sheet. The speed advantage is real in some cases, but it doesn’t change the underlying pricing structure — you’re working with one lender’s rates, not a competitive wholesale market.
Key Features
Speed-to-Close Model: Retail lender with an operational focus on faster processing and closing timelines.
Conventional, FHA, and VA Refinance: Standard refinance products for existing borrowers.
Mission-Driven Model: Community reinvestment focus that resonates with some borrowers.
Single-Shelf Pricing: Retail channel only — one institution’s rate sheet, not wholesale market access.
Best For
Borrowers who value a fast, process-oriented refinance experience and are less focused on rate optimization. If minimizing payment is the goal, comparing Movement’s retail quote against wholesale pricing gives you a complete picture.
Pricing
Retail channel pricing; contact Movement Mortgage directly for current rate quotes.
5. Rocket Mortgage — Digital Rate-and-Term Refinance
Best for: Tech-comfortable borrowers who want a fully self-service digital refinance experience without speaking to a loan officer.
Rocket Mortgage is a large national direct-to-consumer retail lender offering a fully digital refinance application process for conventional, FHA, and VA loans, with self-service tools and online rate estimates.
Where This Tool Shines
Rocket Mortgage’s digital experience is genuinely polished. The application process is intuitive, the self-service tools are well-built, and borrowers who want to move through a refinance without phone calls or in-person meetings will find the platform accommodating.
The structural limitation is significant for rate-focused borrowers: Rocket Mortgage is a large retail and direct lender. It cannot access wholesale pricing tiers. When you apply through Rocket, you’re getting one institution’s rate — not the output of 500+ lenders competing for your loan. For Short Pump homeowners with a $480,000+ loan balance, that pricing gap can be meaningful over the life of a refinance.
Key Features
Fully Digital Application: End-to-end online process for borrowers who prefer self-service over advisor-led guidance.
Conventional, FHA, and VA Refinance: Standard refinance products available through the digital platform.
Online Rate Estimates: Self-service rate tools available without speaking to a loan officer.
Single Institution Pricing: Large retail and direct lender — wholesale market pricing is not accessible through this channel.
Best For
Borrowers who prioritize digital convenience and are comfortable navigating a refinance independently. Using Rocket’s online tools to generate a rate quote and then comparing it against a wholesale broker’s pricing is a practical way to benchmark the market.
Pricing
Retail and direct channel pricing; rates and fees vary. Online rate quotes available on their website.
6. FHA Streamline Refinance — Reduced-Documentation Rate Reduction
Best for: Short Pump homeowners with existing FHA loans who want to lower their rate quickly with minimal paperwork.
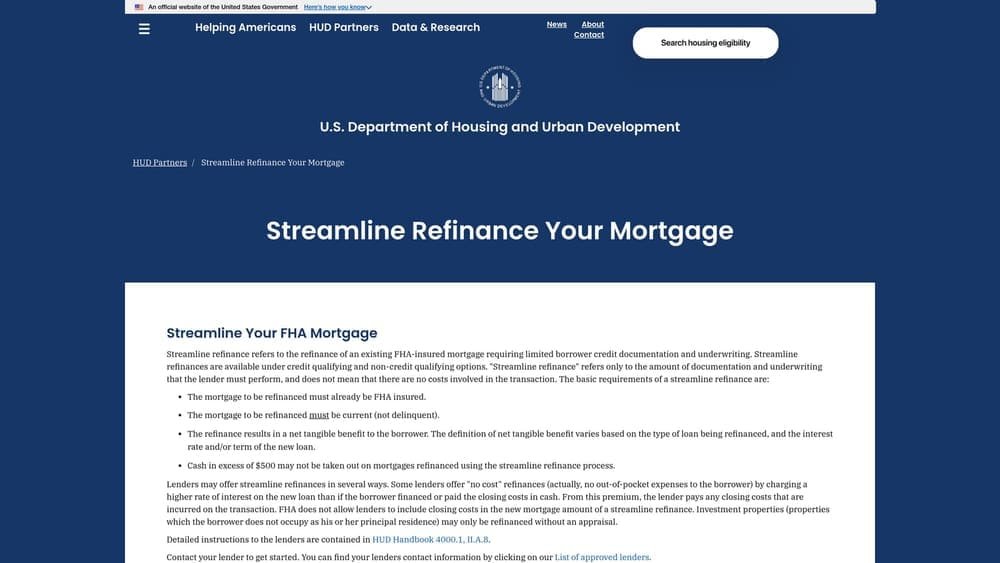
The FHA Streamline Refinance is a government-backed program allowing existing FHA borrowers to reduce their interest rate with minimal documentation — no appraisal required and no income re-verification in most non-credit qualifying cases.
Where This Tool Shines
The Streamline’s power is in what it eliminates. No appraisal means your current home value doesn’t matter — even if you’re concerned about equity, you can still refinance if you have an existing FHA loan in good standing. No income re-verification removes another common obstacle. The process is genuinely faster and simpler than a standard refinance.
The key variable is who you use to access it. The FHA Streamline program is available through any FHA-approved broker or lender — but the rate you get depends entirely on who submits your file. An independent wholesale broker can submit to multiple FHA-approved wholesale lenders simultaneously, while a retail lender offers only their single institution’s pricing on the same government program.
Key Features
No Appraisal Required: Home value is not a factor in most FHA Streamline transactions — simplifies and speeds the process.
No Income Re-Verification: Non-credit qualifying streamlines do not require updated income documentation in most cases.
Existing FHA Loan Required: Only available to borrowers with a current FHA loan in good standing.
Net Tangible Benefit Requirement: The new rate must result in a defined improvement — the program is designed to produce a real payment reduction.
Broker Access Advantage: Accessing this program through a wholesale broker rather than a retail lender can yield meaningfully lower rates on the same government program.
Best For
Short Pump homeowners who purchased with an FHA loan and are carrying a rate above current market levels. Particularly effective for borrowers who bought in 2022 or 2023 at peak rates and want a faster, lower-cost path to payment reduction.
Pricing
Closing costs apply and can often be structured as no-out-of-pocket closing options through a rate adjustment. MIP (mortgage insurance premium) continues after the streamline. Broker access can reduce the rate component significantly compared to retail.
7. VA IRRRL — Interest Rate Reduction Refinance Loan for Veterans
Best for: Veterans and active-duty service members in Henrico County with existing VA loans who want the fastest, lowest-cost path to a lower payment.
The VA IRRRL (Interest Rate Reduction Refinance Loan) is a VA-backed refinance program exclusively for veterans and active-duty service members with existing VA loans, allowing a rate reduction with minimal documentation and typically no out-of-pocket costs when structured correctly.
Where This Tool Shines
The VA IRRRL is arguably the most borrower-favorable refinance program in existence. No appraisal, no income verification in most cases, a VA funding fee of only 0.5% that can be financed into the loan, and the ability to structure the transaction with no-out-of-pocket closing options. For qualifying veterans, this is almost always the first solution to evaluate.
As with the FHA Streamline, the rate you receive depends on who processes your IRRRL. Short Pump Mortgage, named Virginia Broker of the Year 2024 and 2025, can submit VA IRRRL applications to multiple wholesale lenders — accessing VA pricing that retail lenders cannot match. VA loans to 500 FICO are available through this channel as well.
Key Features
No Appraisal Required: Home value is not a factor — simplifies and accelerates the process significantly.
No Income Verification: Most VA IRRRL transactions do not require updated income documentation.
0.5% VA Funding Fee: The lowest funding fee tier available on VA loans — and it can be financed into the new loan balance.
Must Lower Rate or Move to Fixed: The IRRRL must result in a lower interest rate or move the borrower from an adjustable-rate to a fixed-rate mortgage.
No-Out-of-Pocket Closing Options: When structured correctly through a wholesale broker, closing costs can be absorbed into the rate with no cash required at closing.
Best For
Any veteran or active-duty service member in Short Pump, Henrico County, or the greater Richmond area with an existing VA loan carrying a rate above current market levels. This is the first call to make — before exploring any other refinance option.
Pricing
VA funding fee of 0.5% applies and is typically financed into the loan. Closing costs vary by lender — broker access through Short Pump Mortgage can reduce the rate component and structure no-out-of-pocket closing options in most cases.
8. PMI Removal + Loan Recasting — Payment Reduction Without Refinancing
Best for: Short Pump homeowners who have built equity since purchase and want to reduce their monthly payment without a new loan, hard credit pull, or closing costs.
PMI cancellation and loan recasting are two servicer-level solutions that reduce monthly payments without requiring a new loan. The CFPB’s PMI cancellation guidance explains your rights as a borrower — including the requirement that servicers cancel PMI automatically at 78% LTV under the Homeowners Protection Act.
Where This Tool Shines
These two strategies are often overlooked because they don’t involve a new loan — but for the right borrower, they’re the most efficient payment reduction available. PMI removal requires no refinance, no hard inquiry, and typically no fee beyond a small administrative charge. If Short Pump home appreciation since your 2021–2023 purchase has pushed your LTV below 80%, you may be eligible to request cancellation right now.
Loan recasting works differently: you make a lump-sum principal payment to your current servicer, who then re-amortizes your remaining balance at the same interest rate. Your rate doesn’t change, but your monthly payment drops because the balance is lower. This is particularly useful for borrowers who received an inheritance, sold another property, or accumulated savings and want to reduce their payment without triggering a full refinance.
Real Dollar Math: PMI Removal Scenario
Consider a Short Pump purchase at $520,000 with 5% down — a $494,000 loan. At a PMI rate within the general industry range of 0.5% to 0.85% annually, a borrower at the midpoint might pay approximately $268 per month in PMI. If that home has appreciated to $600,000 or above (a realistic scenario in the Short Pump market given recent years), the loan-to-value ratio drops below 80% and PMI cancellation becomes eligible. That’s approximately $268 per month saved with no refinance, no hard credit inquiry, and no closing costs. These figures are illustrative and your actual PMI rate is set by your original loan terms.
Key Features
PMI Cancellation at 80% LTV: Request cancellation when your equity reaches 20% — no refinance required, no hard credit pull.
Automatic Cancellation at 78% LTV: Under the Homeowners Protection Act, servicers must cancel PMI automatically at 78% LTV — know your rights.
Loan Recasting: Make a lump-sum principal payment and your servicer re-amortizes the balance at your existing rate — payment drops, no new loan needed.
No Hard Inquiry Required: Neither PMI removal nor loan recasting triggers a hard credit pull.
Short Pump Appreciation Angle: Homeowners who purchased in 2021–2023 may already qualify for PMI removal based on market appreciation alone — worth requesting a servicer review.
Best For
Short Pump and Henrico County homeowners who purchased with less than 20% down, are not looking to change their rate, and want the simplest possible path to a lower monthly payment. Also ideal for borrowers who received a lump sum and want to reduce payments without the cost and timeline of a full refinance.
Pricing
PMI removal is typically free or carries a small administrative fee. Loan recasting fees vary by servicer but commonly range from $150 to $500 — confirm the exact amount with your current servicer before proceeding.
How to Compare Your Options: A Quick Reference
| Solution | Loan Type Required | Hard Credit Pull? | Appraisal Required? | Pricing Access | Best Scenario |
|---|---|---|---|---|---|
| Short Pump Mortgage (Wholesale Broker) | Any — FHA, VA, USDA, Conv, Non-QM | No — NoTouch Credit Pull (soft pull) | Varies by program | 500+ wholesale lenders competing | Any homeowner wanting lowest available rate |
| Sparrow Home Loans | Conventional, FHA | Yes (retail process) | Typically yes | Single retail institution | Borrowers preferring local in-person service |
| C&F Mortgage Corp | Conventional, FHA, VA | Yes (retail process) | Typically yes | Single retail institution | VA regional lender preference |
| Movement Mortgage | Conventional, FHA, VA | Yes (retail process) | Typically yes | Single retail institution | Speed-focused retail borrowers |
| Rocket Mortgage | Conventional, FHA, VA | Yes (digital process) | Typically yes | Single retail/direct institution | Self-service digital preference |
| FHA Streamline Refinance | Existing FHA loan required | No (non-credit qualifying) | No | Depends on broker vs. retail access | FHA borrowers at above-market rates |
| VA IRRRL | Existing VA loan required | Minimal | No | Depends on broker vs. retail access | Veterans with VA loans above market rate |
| PMI Removal + Loan Recast | Any — with PMI or lump sum available | No | No (servicer review only) | N/A — servicer-level action | Equity-rich homeowners; no rate change needed |
Frequently Asked Questions: Short Pump & Henrico County Mortgage Payment Solutions
1. Can I lower my mortgage payment without refinancing in Henrico County? Yes — PMI removal and loan recasting are two options that reduce your payment without requiring a new loan or hard credit inquiry. If you purchased with less than 20% down and your home has appreciated, PMI cancellation may be available immediately by contacting your servicer.
2. What is a NoTouch Credit Pull and how does it help Short Pump homeowners? A NoTouch Credit Pull is a soft credit inquiry that lets you explore refinance options and get rate quotes without any impact to your credit score. Short Pump Mortgage uses this mortgage pre approval without hard pull approach so you can see real wholesale pricing before deciding whether to move forward.
3. Does Short Pump Mortgage offer FHA Streamline Refinances? Yes — as an FHA-approved broker, Short Pump Mortgage can submit FHA Streamline applications to multiple wholesale lenders simultaneously, finding the lowest available rate on the same government program that retail lenders offer at a single institution’s pricing.
4. What is the VA IRRRL and who qualifies in Henrico County? The VA Interest Rate Reduction Refinance Loan is available to any veteran or active-duty service member with an existing VA loan, allowing a rate reduction with no appraisal and typically no out-of-pocket costs. If you have a VA loan and your current rate is above market, this is the first option to evaluate.
5. How much equity do I need to remove PMI on my Short Pump home? You generally need 20% equity (80% LTV) to request PMI cancellation. Given Short Pump median home prices and appreciation trends, many 2022–2023 buyers may already qualify — contact your servicer for a current LTV review before assuming you still need to carry PMI.
6. Can a mortgage broker get me a lower rate than Rocket Mortgage or a retail lender? Often yes — an independent broker like Short Pump Mortgage shops 500+ wholesale lenders simultaneously, accessing pricing tiers that retail lenders cannot offer. The structural difference is that retail loan officers can only offer their single institution’s rate sheet, while a wholesale broker submits to the entire market.
7. What is the FHFA 2026 conforming loan limit for Henrico County? The 2026 FHFA baseline conforming limit is $806,500, which covers the vast majority of Short Pump and Henrico County home purchases at or near the current median price. This means most local homeowners have access to conventional conforming refinance products without entering jumbo territory.
8. How long does a mortgage refinance take in Short Pump VA? A standard rate-and-term refinance typically closes in 21 to 30 days. FHA Streamline and VA IRRRL refinances can often close faster due to reduced documentation requirements — no appraisal and no income re-verification in most cases shortens the timeline meaningfully.
Finding the Right Solution for Your Situation
Here’s the short version: match your loan type to your best path forward.
If you’re a veteran with an existing VA loan, start with the VA IRRRL. No appraisal, no income verification, 0.5% funding fee, and no-out-of-pocket closing options when structured correctly. It’s the most borrower-favorable refinance program available and should be the first call for any qualifying veteran in Henrico County.
If you have an existing FHA loan, the FHA Streamline is your fastest path. No appraisal, minimal documentation, and a process that moves faster than a standard refinance. The rate you get depends on who you work with — wholesale broker access consistently outperforms retail pricing on the same program.
If you’re carrying PMI or have received a lump sum, explore PMI removal and loan recasting before initiating any refinance. These are free or near-free solutions that require no new loan and no hard credit inquiry. Many Short Pump homeowners who purchased in 2021 through 2023 qualify right now and don’t realize it.
For anyone unsure where they stand, the NoTouch Credit Pull through Short Pump Mortgage is the logical starting point. You get real wholesale pricing across 500+ lenders with no credit score impact — a true soft pull mortgage broker approach that lets you see your actual options before committing to anything. That’s a no hard inquiry mortgage pre approval with real numbers attached.
Connect with our local mortgage experts today to start a no-credit-hit mortgage application, explore your refinance options across the wholesale market, and find out which solution fits your situation. Call (804) 212-8663 or start online.
Duane Buziak is a Scotsman Guide Top Originator 2025 (#114, $44.4M) and 2026 ($51.2M), UWM PRO ELITE 2025, and Virginia Broker of the Year 2024 and 2025 — with 1,400+ five-star reviews (488 Google at 4.98 stars, 975 Experience.com at 4.98 stars) from Short Pump, Henrico County, and Richmond-area homeowners. More refinancing resources and mortgage tips are available on the site.